For a D2C business, the amount deposited by an online marketplace rarely equals the gross value of customer orders. Returns, cancellations, shipping, commissions, payment-related fees, tax adjustments and settlement timing can all affect the money received. This is why marketplace settlement reconciliation is a core control, not an optional accounting exercise.
A reliable process connects the platform's orders and adjustments with accounting entries and actual bank credits, while preserving a trail back to source records.
Why the bank credit is not your sales figure
Suppose a marketplace reports customer orders of ₹1,00,000 during a period. An illustrative settlement summary might show:
| Settlement component | Example amount |
|---|---|
| Gross reported order value | ₹1,00,000 |
| Returns/refunds | (₹10,000) |
| Marketplace fees | (₹12,000) |
| Shipping and fulfilment deductions | (₹3,000) |
| Illustrative net before other tax/settlement adjustments | ₹75,000 |
The ₹75,000 is not automatically the correct accounting revenue or the final bank amount. Tax treatment, additional withholdings, platform-specific adjustments and unsettled transactions must be evaluated from actual reports. The example simply shows why recording the net settlement as “sales” can hide the underlying activity.
What should be reconciled?
1. Orders, invoices and cancellations
Start with the platform order report and the business's invoice records. Check whether cancelled orders generated invoices, whether credit notes were issued for returns and whether the reporting period aligns with the accounting period.
2. Returns, refunds and chargebacks
Track the full return lifecycle. A return may be requested in one period, physically received later and financially adjusted in a different settlement. Distinguish refunded orders from exchanges, damaged returns and claims against the platform.
3. Marketplace fees and deductions
Map commission, shipping, advertising, fulfilment, penalties and other deductions to suitable expense or control accounts under the agreed accounting policy. Keep supporting statements and tax documents for those charges. Unidentified deductions should remain exceptions for investigation rather than being silently posted to a generic expense head.
4. Payouts and bank receipts
Match each settlement reference with the relevant bank credit. A difference may arise because the platform has retained part of a balance, made a timing adjustment, deducted fees or combined transactions from several days.
5. Accounting stock movements
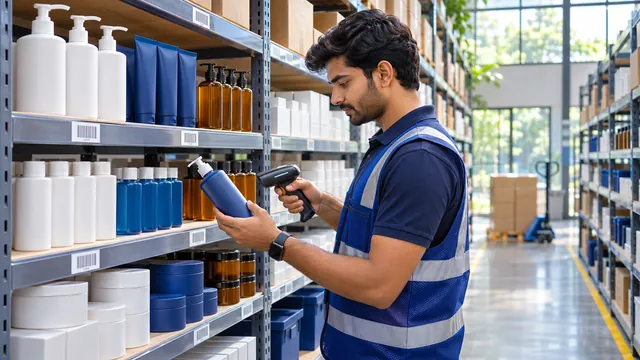
Sales, returns, warehouse transfers, damages and approved adjustments affect stock records. If SKU codes differ between the platform, warehouse system and accounts, an apparently simple reconciliation can become unreliable. Fix master-data mapping before drawing conclusions from SKU-level profitability or stock balances.
A practical reconciliation workflow
- Download complete exports for orders, invoices, settlements, fees, refunds and stock movement for the agreed period.
- Standardise identifiers such as order ID, settlement ID, SKU, invoice number, transaction date and channel.
- Match gross activity to invoices, refunds and approved accounting adjustments.
- Classify fees and deductions with supporting detail rather than relying only on net payouts.
- Reconcile to bank using payout references and highlight unsettled or unexplained balances.
- Review stock differences against client-supplied warehouse and movement records.
- Close with an exception list stating the unresolved amount, owner and expected follow-up.
The method may use invoice-wise or controlled batch/settlement-wise postings depending on source quality, software capability and statutory record requirements. Whichever method is used, the underlying source trail needs to remain retrievable.
Four common reconciliation problems
Mismatch in SKU codes. One product may appear under several names or IDs. A master SKU mapping and consistent units of measure reduce avoidable errors.
Returns reported in a different month. Use a clear period cutoff and track pending refund or return statuses separately.
Fees posted as a single unexplained deduction. This makes margin analysis unreliable and may conceal incorrect charges.
Stock treated as physically verified. An accounting stock record is based on supplied movements and approved counts. It does not prove physical quantities unless the responsible business team has performed and documented a stocktake.
When does a seller need more than basic bookkeeping?
Multi-channel selling creates volume, timing and data challenges. A seller may need additional reporting when returns are high, fulfilment models differ, there are multiple warehouses, or settlement exceptions recur. Even a business with relatively few accounting vouchers may have thousands of platform-level order and adjustment records to reconcile.
PROFINZO Accounts Growth Commerce is designed for defined D2C and marketplace accounting scopes, including agreed selling platforms, settlement reconciliations and SKU-wise accounting stock records from complete client-supplied data. It does not replace warehouse operations or physical stock verification.
Frequently asked questions
Can a marketplace payout be recorded directly as total sales? Generally, it is not sufficient without reconciling gross orders, credits, fees, taxes and other adjustments.
Are Amazon and Flipkart exports identical? No. The format and availability of reports differ by channel and can change over time; mappings must be checked against the actual data.
Does accounting stock equal a physical count? No. Physical verification and approval of stock differences remain operational responsibilities.
Is marketplace reconciliation the same as profitability analysis? No. Reconciliation establishes reliable activity and balances; channel/product profitability may require additional allocation policies and reporting.
Next step: Discuss your marketplace accounting workflow with PROFINZO.